
3 November 2026

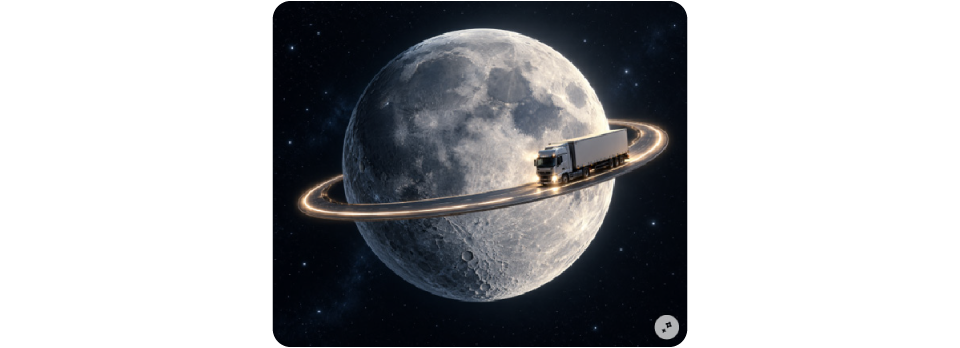
Transportation – air, road or sea – is a global industry. Airlines carry nearly 5 billion passengers a year; over 6,000 container ships move goods worldwide. Heavy-duty trucks travel almost 200 billion miles a year in the US alone, equivalent to about 400,000 round trips to the Moon.

This industrial transport puts a heavy strain on our global energy system and the emissions are substantial: all in, industrial transport contributes to 10.5% of global CO₂ emissions1 and continues to grow.
At Climate Investment (CI), we believe there will be a mix of both electrification and lower-carbon fuels to decarbonize transport.
Electrification is important but for long-haul aviation, ocean shipping and heavy-duty trucking, a combination of energy density, infrastructure and equipment replacement cycles makes switching to electric challenging.
By contrast, the customer attraction to lower-carbon fuels is to reduce lifecycle emissions without requiring every operator to first buy a new vehicle, aircraft or vessel.
However, low-carbon fuels face their own challenge: feedstock is a major cost, and supply remains fragmented, logistically complex and difficult to verify. Unlocking additional certified and compliant sources is therefore critical to scaling low carbon fuels.
There are several low-carbon fuels already on the market:
The GHG impact of low carbon fuels is meaningful: RD versus fossil, and SAF versus jet fuel can reduce CO2 emissions around 80%2.
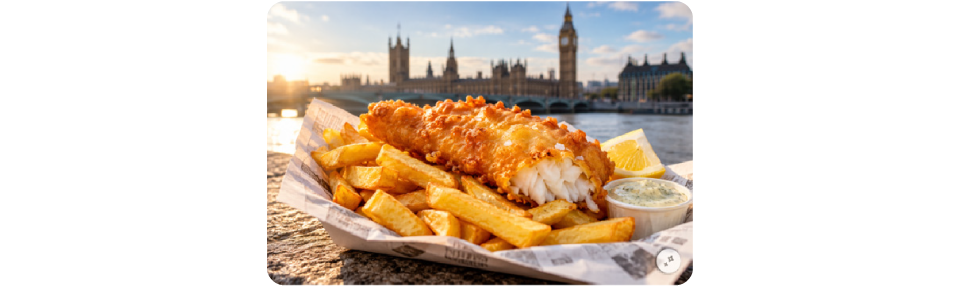
You may be surprised to hear that existing waste from our Fish & Chips eating habits can be converted to a productive use within the global transport ecosystem.
In the UK alone, there are 5 portions of Fish & Chips sold every second! And Brits are not alone in loving fried foods – worldwide, we eat 1000’s of portions of French fries every second. Add fried chicken, samosas, donuts, falafels, and churros; the scale of global frying oil consumption is enormous.

How big? In 2022, 3.7 billion gallons of used cooking oil was collected globally, projecting 5–10 billion gallons by 2030, with broader global potential of ~17 billion gallons (77 billion litres)3 if countries establish collection networks and overcome collection barriers. Not all used cooking oil makes its way to fuel today, so driving this large increase to the sector is important to unlocking higher production.
A restaurant’s waste oil is not yet refinery-ready feedstock. It must be collected economically, aggregated, treated, tested, traced to its origin and delivered on schedule. Producers need evidence that it is genuine waste, that complies with applicable requirements and meets processing specifications.
And, used cooking oil is only one of many types of feedstock for low-carbon fuels.
Fuel feedstocks come from a wide range of sources, including used cooking oil, animal fats, distillers corn oil, ethanol and other renewable inputs.
All the pathways produce usable fuel molecules, but the carbon footprint and cost differ considerably by pathway, as we explore the details below.
Cost remains one of the biggest barriers to wider adoption of low-carbon fuels.
For trucking, the industry primarily uses the HEFA pathway to make renewable diesel, a drop-in replacement. Feedstock costs and policy support are the key drivers for cost-parity to fossil.
The rhetoric of “we do not have enough feedstock” is not a volume issue, it is a supply chain issue; there are 4x the volumes available for used cooking oil than what is utilized today, if we could collect, aggregate, and source it more efficiently. And of course, there are other feedstocks such as distillers corn oil, soybean, and more that go into the end mix for a fuel producer.
The barrier to more feedstock is fragmentation and a long sequence of intermediaries, making it costly and operationally complex to meet industrial-scale demand. Before feedstocks can become fuel, they must be identified, verified, documented, aggregated, transported and matched with the right buyer.
Fuel producers need sufficient volumes of verified feedstock at the right quality, price, quantity and location. In many markets, particularly in the US, traceability and certification are key to economics. Producers need feedstocks that meet specifications and verified origin and chain of custody to satisfy regulatory and credit requirements. Simplifying this certification burden is important to unlocking new, additional supply.
For aviation, costs vary substantially by production pathway. HEFA and ATJ are among the most cost-competitive pathways today, while electricity-intensive e-fuels remain substantially more expensive. Compared to conventional fuel6, competitive SAF pathways still carry a substantial cost premium:
At CI, we believe that the near-term pathway will continue to be dominated by HEFA and AtJ, with e-SAF playing a larger role in the longer-term. For HEFA7 and ATJ8, feedstock costs remain the single biggest lever for cost reduction.
CI co-led the Series A investment in WayTrade with Autotech Ventures.
WayTrade’s marketplace and workflow logistics software platform is designed to make low-carbon feedstock supply chains more efficient, transparent and reliable, drawing on the team’s first-hand experience trading feedstocks.
WayTrade connects feedstock suppliers with fuel producers, and helps coordinate sourcing, quality testing, transportation, tracking, documentation and payments, with a higher level of auditability. Rather than producing fuel or collecting feedstock itself, it enables existing participants to transact more efficiently, manage trade execution, and reduce risk through a single platform.
We see an opportunity to reduce the costs of fragmented sourcing, duplicated administration and inefficient logistics. Better visibility can help suppliers reach buyers, producers plan purchases, and both sides manage delivery and compliance. Independent certification and verification are essential.
The WayTrade business grows by connecting more suppliers, buyers and logistics partners rather than building additional refineries. A larger network can improve matching and operational efficiency, creating value for participants and a more defensible platform – the Flywheel Effect.
And the platform can expand beyond fuels – WayTrade’s technology can serve other waste-derived feedstocks used in chemicals and plastics.
WayTrade’s flexibility is central to our investment thesis. Their platform is not fixed to one end market: it can serve producers as demand shifts between road, air and marine. That flexibility also extends to policy: changes in feedstock eligibility, origin requirements and incentives impact economics. An investment not tied to a single production asset, feedstock or technology.
The market opportunity is massive. The global transport fuel market including road, aviation, maritime and rail is $4.5 trillion, of which heavy transport represents 50%9. Fuel is the #1 cost element, and also the #1 emissions element.
We believe low-carbon fuel solutions will inevitably continue to increase compared to fossil diesel. Nonetheless, the penetration today is still relatively low – with Renewable Diesel only ~4% of trucking fuel in US10, and SAF only 0.8% of aviation fuel use11.
We see the WayTrade platform supporting the growth of lower-carbon fuels to decarbonize industrial transport by eliminated structural supply chain barriers and unlocking new feedstock volumes.
Marketplace builders. Proven operators. The team brings decades of experience building and scaling marketplaces and tackling fragmented supply chains at Hubba, Uber, and Gopuff.
For CI, our investment conviction combines substantial emissions-reduction potential in global industrial transport with technology that enables greater efficiency and lower operational costs.
WayTrade delivers aggregated, verified feedstock which can in turn help producers protect margins, strengthen supply resilience, and scale established low carbon fuel using infrastructure already in place.
1 Aviation, shipping, road freight and rail together emitted ~ 4.2B tons of CO₂ in 2018: aviation 0.93B, shipping 0.85B, road freight 2.35B, and rail 0.08B. Includes passenger aviation and rail. Calculated from IEA data presented by Our World in Data (2020).
2 Lifecycle intensity calculation based on UK Department for Transport, RTFO Guidance 2022, Annex C; EU fossil-fuel comparator; ICAO CORSIA default lifecycle values, November 2025, Table 2; ICAO jet-fuel baseline; renewable diesel using HEFA and UCO of16 gCO₂e/MJ, compared with a fossil transport-fuel of 94 gCO₂e/MJ; of HEFA SAF 13.9 gCO₂e/MJ compared with conventional jet fuel: 89 gCO₂e/MJ
3 LMC International/GlobalData (2023), Global Supply and Trade of Used Cooking Oil, commissioned by Clean Fuels Alliance America, pp. 1 and 5.
4 IATA and Worley Consulting (September 2025), Global Feedstock Assessment for SAF Production: Outlook to 2050, section 6.3, p. 23. The forecast applies project-specific success factors to the announced project pipeline and estimates approximately 20 million tonnes of global annual SAF capacity by 2030.
5 Macquarie’s May 2025 article, From field to fuel: Biofuels’ feedstock dilemma
6 ICAO; UK Department for Transport; EASA, ReFuelEU Aviation Annual Technical Report 2026. Figures are indicative estimates informed by multiple sources. Actual costs vary by pathway, feedstock, geography and plant maturity.
7 Nordic Council of Ministers’ Sustainable Jet Fuel for Aviation (2016), section 9.5.4, p. 173 estimates feedstock at 60–80% of production costs for its HEFA/HEFA+ scenario,
8 Tanzil et al. (2021), Evaluation of dry corn ethanol bio-refinery concepts for the production of sustainable aviation fuel, Biomass and Bioenergy, 146, 105937. Note, corn sourcing constitutes the majority of the operational cost with 60% of the yearly OPEX, and does not include conversion from corn to ethanol
9 IEA study https://www.iea.org/data-and-statistics/data-tools/renewable-energy-progress-tracker, representing 3.2 trillion liters per year using an average of $1.4/liter
10 US Energy Information Administration, Low U.S. distillate consumption reflects slow economic activity and biofuel substitution, 25 April 2024.
11 Projected by year end 2026. International Air Transport Association, SAF Production Volumes Still Disappointing, 6 June 2026.
Disclaimer Clause
This publication contains certain forward-looking statements – that is, statements related to future, not past events and circumstances – which may relate to the ambitions, aims, targets, plans and objectives of OGCI Climate Investments LLP or its subsidiaries (“CI”) and/ or its member companies. These use expressions such as “accelerate”, “advance”, “aim”, “ambition”, “commit”, “expect”, “plans”, “strive”, “target” and “will” or similar expressions intended to identify such forward-looking statements. Forward looking statements involve risk and uncertainty because they relate to events and depend on circumstances that will or may occur in the future and are outside of the control of CI and/or its member companies. Actual results or outcomes may differ from those expressed in such statements, depending on a variety of factors. CI does not undertake to publicly update or revise these forward-looking statements, even if experience or future changes make it clear that the projected performance, conditions or events expressed or implied therein will not be realized. © 2026, OGCI Climate Investments LLP. All rights reserved.